
Scope 3 Category 4 upstream transportation and distribution examples
The original synthetic editorial scene shows an unbranded articulated truck backed to an industrial loading dock, wrapped pallets and a forklift beside a warehouse entrance. It provides logistics context only; it cannot establish a reporting company, asset control, purchased-service status, Category 4 classification or measured emissions.
Diagram text description
Scope 3 Category 4 upstream transportation and distribution examples are useful only when the reporting company and its relationship to the activity are clear. A truck heading toward a factory, an outward delivery and an independent warehouse can all raise Category 4 questions. Their direction or appearance alone does not settle the accounting.
Start with the company boundary, identify the purchased goods or service, and check who controls the vehicles or facilities. Then reconcile overlap with supplier and carrier records, select compatible calculation inputs and review the result. Keep classification evidence attached to the total rather than allowing the formula to decide the category.
Identify the reporting company and the movement or service. Check asset control and the purchased-goods or purchased-service relationship, retaining relevant contract and payment evidence. Resolve overlap with supplier or carrier data, choose compatible activity and factor inputs, then review the Category 4 record. A vehicle type alone cannot determine the category.
Diagram text description
GHG Protocol’s Category 4 guidance distinguishes transport of purchased products between tier 1 suppliers and company operations from other purchased third-party logistics services. Those services can include outbound and interfacility movements. The fictional cases below show the contractual and control evidence behind each decision, followed by a reproducible transport calculation. They illustrate the method without supplying verified customer data or operational factors.
Start with the reporting company and purchased service
Define whose inventory you are preparing. The buyer, supplier and carrier can have different reporting relationships to one physical movement. The carrier may operate the vehicle and consume its fuel; the buyer may receive purchased goods; the supplier may arrange delivery under its sales contract. Those perspectives need separate boundary assessments.
Category 4 has two relevant entry routes: transport and distribution of purchased products from tier 1 suppliers to the company’s operations in outside vehicles or facilities, and third-party transport or distribution services purchased by the reporting company. The latter includes services bought through an intermediary, outbound distribution and transfers between company facilities.
Keep the purchase order, delivery terms, service contract and payment evidence, together with the ownership/control assessment. Payment is especially useful for distinguishing a company-purchased outbound service from a customer-purchased downstream movement. A separate carrier invoice paid by the reporting company is not a prerequisite for the tier 1 inbound purchased-goods route.
For example, supplier-arranged delivery of purchased material can still enter the buyer’s Category 4 boundary. Determine which physical leg a supplier footprint covers before adding a carrier result. An embedded price or a supplier’s invoice format cannot replace the tier, route and overlap checks. Record the applicable reporting year and consolidation policy so the decision can be repeated consistently.
Five concrete examples and their boundary tests
Explicitly fictional case comparison: every company, contract and payment below is invented. Brook Manufacturing is the reporting company except in the Cedar Retail transfer row. Each result assumes the stated consolidation boundary; the changed condition shows why the evidence matters.
| Fictional case | Contract, payment and control evidence | Initial treatment | Changed condition and effect |
|---|---|---|---|
| Brook inbound material | PO B-41 buys resin from a tier 1 supplier; Brook pays independent carrier C-17; Brook has no vehicle control | Category 4 for the supplier-to-Brook movement | Brook instead controls and operates the diesel truck: assess its fuel in Scope 1 |
| Brook outbound sale | Contract D-22 buys independent delivery of sold goods; Brook pays the carrier and controls no transport asset | Category 4 purchased outbound service | Customer separately purchases the onward service and Brook does not pay: assess Brook’s downstream Category 9 boundary |
| Brook warehouse | Storage contract W-08 and invoice buy space at an independently operated facility; Brook controls no building or energy systems | Category 4 purchased distribution service | Brook controls the facility within its boundary: assess fuel and purchased electricity in Scope 1 and Scope 2 |
| Cedar retailer transfer | Cedar moves stock between its own sites using a diesel fleet inside its control boundary; internal dispatch R-14 shows no outside carriage purchase | Scope 1 for controlled diesel combustion, rather than Category 4 | Cedar purchases the transfer from an independent carrier: Category 4 service assessment |
| Brook customer-arranged onward freight | After sale, customer Orchard buys independent onward carriage; no Brook payment or asset control; customer order O-53 identifies purchaser | Category 9 assessment for Brook, outside Category 4 | Brook becomes purchaser of that outside service: Category 4 assessment |
Table 1, shown one row at a time. Every field is retained.
Row 1
- Fictional case
- Brook inbound material
- Contract, payment and control evidence
- PO B-41 buys resin from a tier 1 supplier; Brook pays independent carrier C-17; Brook has no vehicle control
- Initial treatment
- Category 4 for the supplier-to-Brook movement
- Changed condition and effect
- Brook instead controls and operates the diesel truck: assess its fuel in Scope 1
Row 2
- Fictional case
- Brook outbound sale
- Contract, payment and control evidence
- Contract D-22 buys independent delivery of sold goods; Brook pays the carrier and controls no transport asset
- Initial treatment
- Category 4 purchased outbound service
- Changed condition and effect
- Customer separately purchases the onward service and Brook does not pay: assess Brook’s downstream Category 9 boundary
Row 3
- Fictional case
- Brook warehouse
- Contract, payment and control evidence
- Storage contract W-08 and invoice buy space at an independently operated facility; Brook controls no building or energy systems
- Initial treatment
- Category 4 purchased distribution service
- Changed condition and effect
- Brook controls the facility within its boundary: assess fuel and purchased electricity in Scope 1 and Scope 2
Row 4
- Fictional case
- Cedar retailer transfer
- Contract, payment and control evidence
- Cedar moves stock between its own sites using a diesel fleet inside its control boundary; internal dispatch R-14 shows no outside carriage purchase
- Initial treatment
- Scope 1 for controlled diesel combustion, rather than Category 4
- Changed condition and effect
- Cedar purchases the transfer from an independent carrier: Category 4 service assessment
Row 5
- Fictional case
- Brook customer-arranged onward freight
- Contract, payment and control evidence
- After sale, customer Orchard buys independent onward carriage; no Brook payment or asset control; customer order O-53 identifies purchaser
- Initial treatment
- Category 9 assessment for Brook, outside Category 4
- Changed condition and effect
- Brook becomes purchaser of that outside service: Category 4 assessment
These are five distinct evidence patterns, not five vehicle types. The retailer transfer also demonstrates the controlled-fleet exception. For an actual file, verify the contract substance, reporting entity and control policy before adopting the illustrated treatment. A missing payment record leaves a question to resolve; it does not establish either party’s responsibility.
Inbound material from supplier to factory
For purchased materials, distinguish the tier 1 supplier-to-company leg from transport farther upstream. The former falls within the Category 4 purchased-goods boundary when outside vehicles or facilities perform it. Transport between a tier 2 supplier and the tier 1 supplier is part of Category 1 purchased-goods coverage in the guidance.
Supplier footprints and carrier invoices can describe overlapping activity. Ask whether the supplier’s factor ends at its factory gate or includes delivery to your operation. Map the included route against the separately recorded carrier leg, and reconcile the overlap before adding totals.
In Brook’s fictional B-41 case, the carrier contract and invoice establish separately purchased carriage, while the material purchase order establishes the goods relationship. If the supplier instead bundles that same inbound delivery into its price, the physical tier 1-to-Brook boundary remains relevant. Do not automatically move it into Category 1 merely because the supplier arranged payment.
Retain the source factor and any reconciliation adjustment so the reviewer can trace the change. An unresolved overlap should remain visible until the process coverage is understood; a tidy category total is not a reason to count one leg twice.
Outbound delivery paid for by the seller
A seller’s purchased third-party outbound distribution can belong in Category 4. The service is upstream in the purchased-service sense even though the sold product moves outward. The official category description explicitly includes this relationship.
For Brook’s fictional D-22 delivery, the useful evidence is the carrier service contract, Brook’s purchase and payment record, the delivery identity and confirmation that the transport asset is outside Brook’s control. The sales invoice alone does not show who purchased every logistics leg.
For the reporting seller, a third-party outbound distribution service it purchases is Category 4. A downstream movement of sold goods purchased by the customer and not paid for by the reporting seller is assessed under Category 9. Both paths assume vehicles and facilities outside the seller’s ownership or control; controlled transport requires a separate scope assessment.
Diagram text description
A different movement arranged and paid for by Orchard, with no Brook payment or control, is assessed under Brook’s downstream Category 9 boundary. Keep that onward leg separate from any earlier Brook-purchased delivery. Two parties’ documents may describe consecutive services rather than the same contract.
Record the point where the service and purchaser change. Delivery terms can help locate the responsibility, but inspect the actual arrangement rather than classifying every transaction from a shorthand term. A broad statement that all outbound transport is Category 9 would lose the purchased-service distinction that decides these cases.
Third-party distribution centre
Purchased independent storage and distribution need their own activity records. A warehouse service can include energy and refrigerant emissions as well as associated transport, but those activities have different quantities and allocation methods. Separate the service lines before estimating their contributions.
| Activity within the service | Record to request | Allocation or boundary check |
|---|---|---|
| Carrier vehicle energy | Applicable fuel or electricity and movement records | Allocate the relevant transport activity to the company’s goods |
| Warehouse electricity or fuel | Facility meters, bills, period and energy source | Establish the company’s share of the shared storage service |
| Refrigerant leakage | Refrigerant type, leakage quantity and applicable conversion basis | Match the equipment, period and stored-goods service; avoid assuming leakage is zero |
| Average storage estimate | Stored volume or pallets, duration and matching factor | Keep the volume-time denominator and service conditions explicit |
Table 2, shown one row at a time. Every field is retained.
Row 1
- Activity within the service
- Carrier vehicle energy
- Record to request
- Applicable fuel or electricity and movement records
- Allocation or boundary check
- Allocate the relevant transport activity to the company’s goods
Row 2
- Activity within the service
- Warehouse electricity or fuel
- Record to request
- Facility meters, bills, period and energy source
- Allocation or boundary check
- Establish the company’s share of the shared storage service
Row 3
- Activity within the service
- Refrigerant leakage
- Record to request
- Refrigerant type, leakage quantity and applicable conversion basis
- Allocation or boundary check
- Match the equipment, period and stored-goods service; avoid assuming leakage is zero
Row 4
- Activity within the service
- Average storage estimate
- Record to request
- Stored volume or pallets, duration and matching factor
- Allocation or boundary check
- Keep the volume-time denominator and service conditions explicit
For fictional W-08, Brook buys storage at an outside facility. The operator’s entire annual electricity total cannot be assigned to Brook without an allocation basis. Retain the full facility denominator and Brook’s corresponding share, considering occupancy, time and temperature-controlled versus ambient service where relevant.
Check whether a bundled logistics result already includes the warehouse. Adding its energy again would duplicate coverage. Conversely, a transport-only factor does not establish that storage has been included. Record any omitted activity and the reason its evidence remains unresolved.
Cases that should not be added to Category 4
Controlled fleets, supplier/carrier overlaps and unpurchased downstream movements require different checks before anything is added to Category 4. Controlled fuel and electricity belong in the company’s relevant scope assessment. A supplier footprint covering the same inbound leg creates an overlap to reconcile, not permission to add the leg again.
Keep the tier distinction precise. Transport upstream of the tier 1 supplier is included in Category 1 purchased-goods coverage; outside transport from the tier 1 supplier to company operations is within the Category 4 goods boundary. A blanket exclusion for “supplier-embedded freight” would obscure that difference.
Third-party downstream movement of sold goods not paid for by the reporting company is assessed under Category 9. Vehicle manufacture and transport of the company’s consumed fuels or energy have other category routes, so a freight-related description alone does not establish Category 4.
Use a boundary register to retain excluded or reclassified records rather than deleting them. State the physical activity, the reason for its treatment, its destination in the inventory and the evidence owner. This lets a reviewer distinguish a correctly routed activity from a missing source. An unknown control or purchase relationship should remain an open question, with its resolution tracked.
Owned fleet versus purchased transport
Apply the actual consolidation boundary to owned or controlled vehicles before considering purchased transport. For controlled diesel vehicles, direct fuel-combustion emissions enter Scope 1. Purchased electricity used by controlled electric vehicles enters Scope 2. The fact that the vehicles bring goods into the company does not turn those energy activities into Category 4.
Independent carriage purchased by the company follows the Category 4 service assessment. In Cedar’s fictional retailer transfer, an internal dispatch and controlled-fleet record support the scope decision. A new contract with an outside carrier changes the relevant evidence and can change the category treatment even if the route and cargo remain identical.
Within the reporting company’s consolidation boundary, controlled vehicle fuel combustion is assessed in Scope 1 and purchased electricity used by controlled electric vehicles in Scope 2. An independent carrier service purchased by the reporting company is assessed in Category 4. The company boundary, energy source and service contract remain necessary evidence; leased assets need their own boundary review.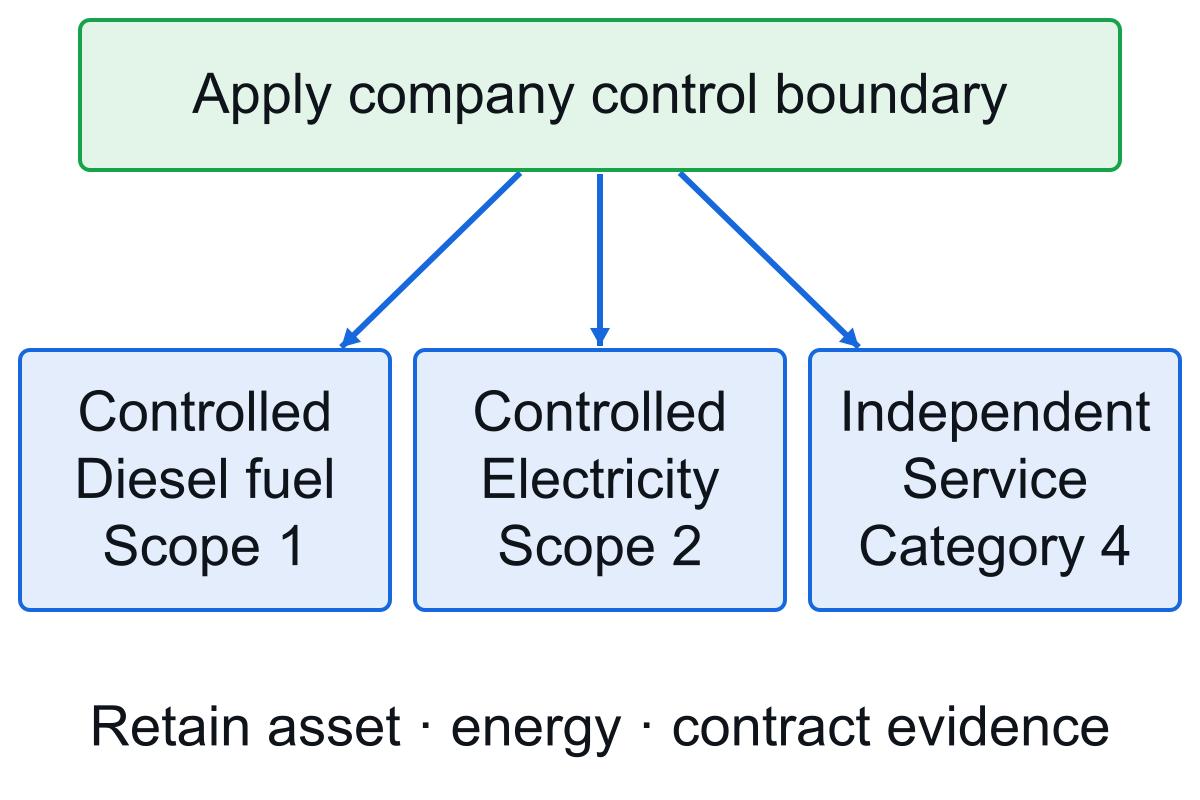
Diagram text description
Retain vehicle identity, control policy, energy source and operating records. If the transport asset is leased, determine its treatment under the company boundary rather than assuming that every lease is either controlled or an independent freight service. The guidance separately identifies upstream leased assets where applicable.
Check the reporting level as well. A subsidiary’s fleet can look external to a local purchasing team while remaining inside the consolidated reporting group. Resolve that entity relationship before importing the carrier-like invoice into a Category 4 register. The accounting follows the reporting company’s boundary and the activity evidence, not the appearance of the bill.
Select fuel, distance or spend data with confidence labels
Choose a method based on the evidence available for the included activity. Suitable carrier fuel data can support an allocated calculation; shipment mass and distance support a distance-based estimate. Spend data can support screening when physical evidence is unavailable, with its uncertainty retained.
| Method | Inputs and allocation evidence | Confidence and compatibility limit |
|---|---|---|
| Fuel-based transport | Relevant fuel type and quantity, energy or refrigerant data where applicable, complete shared-load denominator | Specific records still need correct activity coverage and allocation |
| Distance-based transport | Shipment mass or appropriate volume, each leg’s distance, mode and matching factor | Factor embeds assumptions about vehicle, utilization and service; retain representativeness limits |
| Spend-based screening | Service expenditure by type, currency and price year, applicable monetary factor | Lower-confidence screening; price and service mix obscure physical activity |
| Storage calculation | Site energy/refrigerants and allocated share, or volume-time activity with an average factor | Separate storage conditions and avoid overlap with bundled provider results |
Table 3, shown one row at a time. Every field is retained.
Row 1
- Method
- Fuel-based transport
- Inputs and allocation evidence
- Relevant fuel type and quantity, energy or refrigerant data where applicable, complete shared-load denominator
- Confidence and compatibility limit
- Specific records still need correct activity coverage and allocation
Row 2
- Method
- Distance-based transport
- Inputs and allocation evidence
- Shipment mass or appropriate volume, each leg’s distance, mode and matching factor
- Confidence and compatibility limit
- Factor embeds assumptions about vehicle, utilization and service; retain representativeness limits
Row 3
- Method
- Spend-based screening
- Inputs and allocation evidence
- Service expenditure by type, currency and price year, applicable monetary factor
- Confidence and compatibility limit
- Lower-confidence screening; price and service mix obscure physical activity
Row 4
- Method
- Storage calculation
- Inputs and allocation evidence
- Site energy/refrigerants and allocated share, or volume-time activity with an average factor
- Confidence and compatibility limit
- Separate storage conditions and avoid overlap with bundled provider results
Check both the factor denominator and emissions boundary. A combustion-only fuel factor and a lifecycle factor do not cover the same processes. The guidance discusses lifecycle factors for Scope 3 transport; record the actual dataset’s coverage rather than assuming a familiar unit guarantees compatibility.
Keep gaps specific: missing route distance, unknown load share and an unsuitable factor are different problems. Select an evidence request that resolves the problem affecting the result. Additional decimal places do not compensate for an unverified activity or a mismatched method.
Mass-distance calculation for a transport leg
Explicitly fictional calculation: Brook’s B-41 material uses independent road carriage on leg BR-41-L1 in June 2025. Brook buys the service and controls no vehicle. The assumed truck load is 15 tonnes, including 6 tonnes of Brook goods, all travelling the same 250 km leg. Invented coefficient R-1 version 1 is 0.12 kg CO2e/(t·km), defined here to include fuel combustion and upstream fuel production. It is not a published or verified factor.
| Calculation item | Fictional inputs and arithmetic | Result |
|---|---|---|
| Whole shared load | 15 t × 250 km | 3,750 t·km |
| Whole-load modelled emissions | 3,750 t·km × 0.12 kg CO2e/(t·km) | 450 kg CO2e |
| Brook allocation | 6 t / complete 15 t load = 40%; 450 × 40% | 180 kg CO2e |
| Direct company-activity cross-check | 6 t × 250 km × 0.12 kg CO2e/(t·km) | 180 kg CO2e, same result |
Table 4, shown one row at a time. Every field is retained.
Row 1
- Calculation item
- Whole shared load
- Fictional inputs and arithmetic
- 15 t × 250 km
- Result
- 3,750 t·km
Row 2
- Calculation item
- Whole-load modelled emissions
- Fictional inputs and arithmetic
- 3,750 t·km × 0.12 kg CO2e/(t·km)
- Result
- 450 kg CO2e
Row 3
- Calculation item
- Brook allocation
- Fictional inputs and arithmetic
- 6 t / complete 15 t load = 40%; 450 × 40%
- Result
- 180 kg CO2e
Row 4
- Calculation item
- Direct company-activity cross-check
- Fictional inputs and arithmetic
- 6 t × 250 km × 0.12 kg CO2e/(t·km)
- Result
- 180 kg CO2e, same result
The complete 15-tonne load denominator and common leg distance make the share reproducible. Brook’s direct 1,500 tonne-kilometres already represent its goods. Multiplying that direct answer by 40% again would produce an incorrect 72 kg result. Use one consistent allocation route.
Link the carrier invoice and dispatch record for BR-41-L1 to one activity. Counting each as another 180 kg contribution would create a false 360 kg total. Also reject a vehicle-kilometre coefficient applied to 1,500 tonne-kilometres: the denominator describes a different activity. Confirm packaging and handling-unit treatment in the mass definition for real use.
The 180 kg figure is an invented road-leg result only. Warehouse service, other legs and refrigerants are not calculated here. No additional GWP is applied to the already-CO2e coefficient. Reproduction requires the mass/load manifest, distance basis, service and control evidence, exact factor version and scope, allocation rule and overlap disposition. Spend screening remains a separate, lower-confidence route, never an extra contribution for the same leg.
Spend screening when physical data is missing
Use spend screening when the relevant fuel or mass-distance evidence cannot be obtained, and label the result accordingly. Record the transport service type, amount, currency, price year, geographic basis and monetary factor version. Check whether the amount includes taxes, bundled storage or unrelated services before applying the factor’s specified basis.
A spend factor estimates emissions per unit of economic value. It does not reveal the actual route, vehicle load or fuel consumed. A higher freight price can increase the estimate without any physical increase in transport activity; changes in rates or service mix can also distort comparisons.
Keep screening uncertainty explicit and prioritize better evidence for material sources. If a physical calculation later replaces the screen, retain the earlier estimate and explain the method change. Do not add both estimates for the same service.
For BR-41-L1, the fictional mass-distance record already supplies the teaching result. An invoice amount is useful purchase evidence, but applying a spend factor to that invoice would be an alternative estimate rather than another 180 kg-like item to sum. Compare methods only after their service boundaries and allocation are understood.
Build a reviewable Category 4 register
A Category 4 register should preserve the classification decision and the calculation together. The following filled fictional record reconstructs Brook’s example; it is a teaching record with operational acceptance unresolved.
| Register field | Filled fictional BR-41-L1 entry |
|---|---|
| Company and period | Brook Manufacturing; June 2025; stated company boundary |
| Goods and service | Tier 1 resin purchase B-41; independent road-carriage contract C-17 |
| Control and payment | No Brook vehicle control; Brook carrier invoice/payment reference PAY-17 |
| Physical movement | BR-41-L1; supplier dispatch point to Brook factory; assumed 250 km |
| Quantity and allocation | Brook 6 t within complete 15 t load; all goods on same leg; 40% share |
| Factor and boundary | Invented R-1 version 1; 0.12 kg CO2e/(t·km); fuel combustion plus upstream fuel production |
| Calculation | Whole load 450 kg CO2e × 40% = 180; direct Brook activity also gives 180 |
| Overlap and exclusions | Invoice/dispatch linked once; supplier delivery-factor coverage unresolved; warehouse and other legs unquantified |
| Owner and review | Illustrative Logistics Analyst owns evidence request; hold operational acceptance |
| Revision trigger | Actual manifest, route, control, supplier coverage or applicable factor evidence changes |
Table 5, shown one row at a time. Every field is retained.
Row 1
- Register field
- Company and period
- Filled fictional BR-41-L1 entry
- Brook Manufacturing; June 2025; stated company boundary
Row 2
- Register field
- Goods and service
- Filled fictional BR-41-L1 entry
- Tier 1 resin purchase B-41; independent road-carriage contract C-17
Row 3
- Register field
- Control and payment
- Filled fictional BR-41-L1 entry
- No Brook vehicle control; Brook carrier invoice/payment reference PAY-17
Row 4
- Register field
- Physical movement
- Filled fictional BR-41-L1 entry
- BR-41-L1; supplier dispatch point to Brook factory; assumed 250 km
Row 5
- Register field
- Quantity and allocation
- Filled fictional BR-41-L1 entry
- Brook 6 t within complete 15 t load; all goods on same leg; 40% share
Row 6
- Register field
- Factor and boundary
- Filled fictional BR-41-L1 entry
- Invented R-1 version 1; 0.12 kg CO2e/(t·km); fuel combustion plus upstream fuel production
Row 7
- Register field
- Calculation
- Filled fictional BR-41-L1 entry
- Whole load 450 kg CO2e × 40% = 180; direct Brook activity also gives 180
Row 8
- Register field
- Overlap and exclusions
- Filled fictional BR-41-L1 entry
- Invoice/dispatch linked once; supplier delivery-factor coverage unresolved; warehouse and other legs unquantified
Row 9
- Register field
- Owner and review
- Filled fictional BR-41-L1 entry
- Illustrative Logistics Analyst owns evidence request; hold operational acceptance
Row 10
- Register field
- Revision trigger
- Filled fictional BR-41-L1 entry
- Actual manifest, route, control, supplier coverage or applicable factor evidence changes
Keep unresolved supplier delivery coverage visible even though the arithmetic is complete. A real reviewer needs to establish whether the material factor already includes this leg and document the reconciliation before accepting the category total.
Assign stable identities to warehouse services as well as transport legs. Preserve source files, original units, assumptions and version history so a later update can be explained. A changed route, corrected quantity and revised category decision are distinct reasons for a different result. The register should show which occurred and who reviewed it.
Keep product and logistics evidence connected
Organize product, supplier and shipment evidence so another person can follow the relationship between purchased goods, logistics services and the calculation. A product or bill-of-materials record can identify what moved, while contracts, control evidence and activity records establish the transport or storage treatment.
Check the actual capabilities of any proposed support. Ask how it retains category decisions, factor versions, shared-load denominators, overlap questions and reviewer dispositions. Confirm carrier connections, calculation coverage and assurance scope separately before relying on a service description.
For the next Category 4 record, begin with the reporting company and the purchased-goods or service relationship. Resolve control and overlap, use compatible activity and factors, and retain the result’s limits. The useful outcome is a reproducible, reviewed inventory entry with its unanswered questions visible. An organized evidence structure supports that work; it does not by itself establish a verified factor, completed assurance or permission to publish a claim.
Freight & distribution